
Evan Armstrong is the founder of The Leverage.

Is Anthropic Worth $2 Trillion?
Its IPO filing reveals a remarkable business—and how much has to go right to justify its price
Oct 26, 2026 · 12 min read

Evan Armstrong used to write Napkin Math for Every, and since leaving he’s founded The Leverage, his own publication of clear-eyed analysis of where the tech market is heading. Today we’re teaming back up with him to co-publish his first cut at Anthropic’s S-1, and I loved getting to edit him again. If you like what you read, subscribe to The Leverage.—Kate Lee
Was this newsletter forwarded to you? Sign up to get it in your inbox.
The company whose AI writes marketing copy so bad it makes your eyes bleed is telling you that it is going to cure cancer. This is a ridiculous-sounding claim.
Let me try again.
The fastest-growing company ever, which has more than $100 billion in cash, which will soon control hundreds of billions of dollars’ worth of computing power, which has more than 11,000 customers paying it $100,000 a year, is telling you that it is going to cure cancer. This sounds, to me, marginally more reasonable.
For three years we have understood Anthropic through a deluge of strategic leaks, hyperbole, FUD, jokes about shrimp welfare, memes, and way, way too many blog posts. Now, finally, we have cold, hard, SEC-approved data, through its S-1 filing. This document is absurd. Ridiculous. Stupid. It gives the details on a business the likes of which we have never seen before in the history of capitalism. I’ll give you lots of statistics today, but to start off: Anthropic has raised $141.1 billion since its founding in 2021. As of June 30 it still had $131.7 billion in cash and short-term investments. So the company has burned through less than $10 billion to get to a $16.8 billion quarter. In said quarter, it was even profitable on an operating basis. Again, ridiculous.
Anthropic is reportedly targeting a $2 trillion valuation. Is this valuation equally ridiculous? What do you have to believe to accept this bet? Is it worth investing in this IPO?
Let’s discuss.
Revenue: The most absurd number ever printed
Revenue increased from $376 million in Q1 2025 to $11.6 billion in Q2 2026. The third quarter of this year came in around $16.8 billion, though note that figure is press-reported; the S-1 leaves Q3 blank pending audit review. That is roughly $35 billion of trailing revenue for a company that did not exist six years ago. Yeesh.
What impressed me most was net revenue retention (NRR). Anthropic reports it at approximately 900 percent as of September 30. In MBA-accessible English: The customers who were paying a year ago are now paying nine times as much. For context, the highest NRR any public software company has ever printed is Snowflake’s 189 percent in late 2019, on about $69 million of quarterly product revenue. The public software median is 110 percent. Anthropic did 900 percent on a $16.8 billion quarter. Again, yeesh.
The definitions are not apples to apples (Anthropic’s metric excludes Pro and Max subscribers and counts only “qualified customers”), but still, no one has ever done this before.
That said, don’t over-index on this number. I think of foundation models as being akin to Hollywood, not Silicon Valley SaaS. In Tinseltown, you are only as good as your next movie, and in the LLM game, you are only as good as your next model. The reason they grew ninefold this year is because Anthropic released a series of ever-greater Claude models over the past 12 months (from Opus 4.5 onward). The S-1 backs up my movie business mental model. Anthropic disclosed that models older than six months earn less than 20 percent of revenue. Versions released in the six months up to September 30 produced more than 80 percent of Q3 revenue. So frontier models are an asset with a six-month half-life. As the models themselves get better at making new models, I would expect that half-life to decrease over time.
My second piece of evidence is how clearly the document illustrates Jevons paradox: As AI becomes cheaper and more efficient, people use so much more of it that total spending rises. Essentially, harder tasks have to cost less with each model release for the company to grow. The company says that every release “cuts cost per task 25 to 45%.” For example, after the Opus 4.5 price cut in November 2025, quarter-over-quarter growth went from 48 percent to 132 percent. Translation: Anthropic has to grow volume faster than it cuts price, forever, on a cost base that is contracted years in advance.
My third piece of movie logic evidence is that Anthropic’s growth is already slowing from absurd to merely insane. The second quarter was 144 percent quarter over quarter; the third was about 45 percent. Part of that is the summer, when Fable met real competition from OpenAI and open-weight models for the first time. Part of it is cleanup: The company says 5 to 7 percent of revenue came from customers violating its usage policy, mostly labs distilling Claude, and it cut them off in August and September. (Opus 5.5 appears to have at least partially restored the growth curve, but we’ll see in the next earnings if that is true.)
To believe this company deserves to be in the trillion-dollar club, one of your biggest beliefs needs to be that it can produce better models than the rest of the world, essentially until the end of days.
Who is actually paying?
Despite starting off the S-1 with notes about how Anthropic is in the AGI business, for now, Anthropic is mostly in the Claude Code business. Claude Enterprise users who do not use Claude Code spend less than $75 a month. The top 5 percent of users, who do, spend about $1,500 a month. This is the single most important fact about Anthropic’s growth: The models happened to be the best at coding, the company built the application layer on top of them itself, and via the business strategy magic of vertical integration it captured the value instead of handing it to Cursor and Copilot.
That hasn’t stopped the business from being a B2B monster. A few key points to highlight:
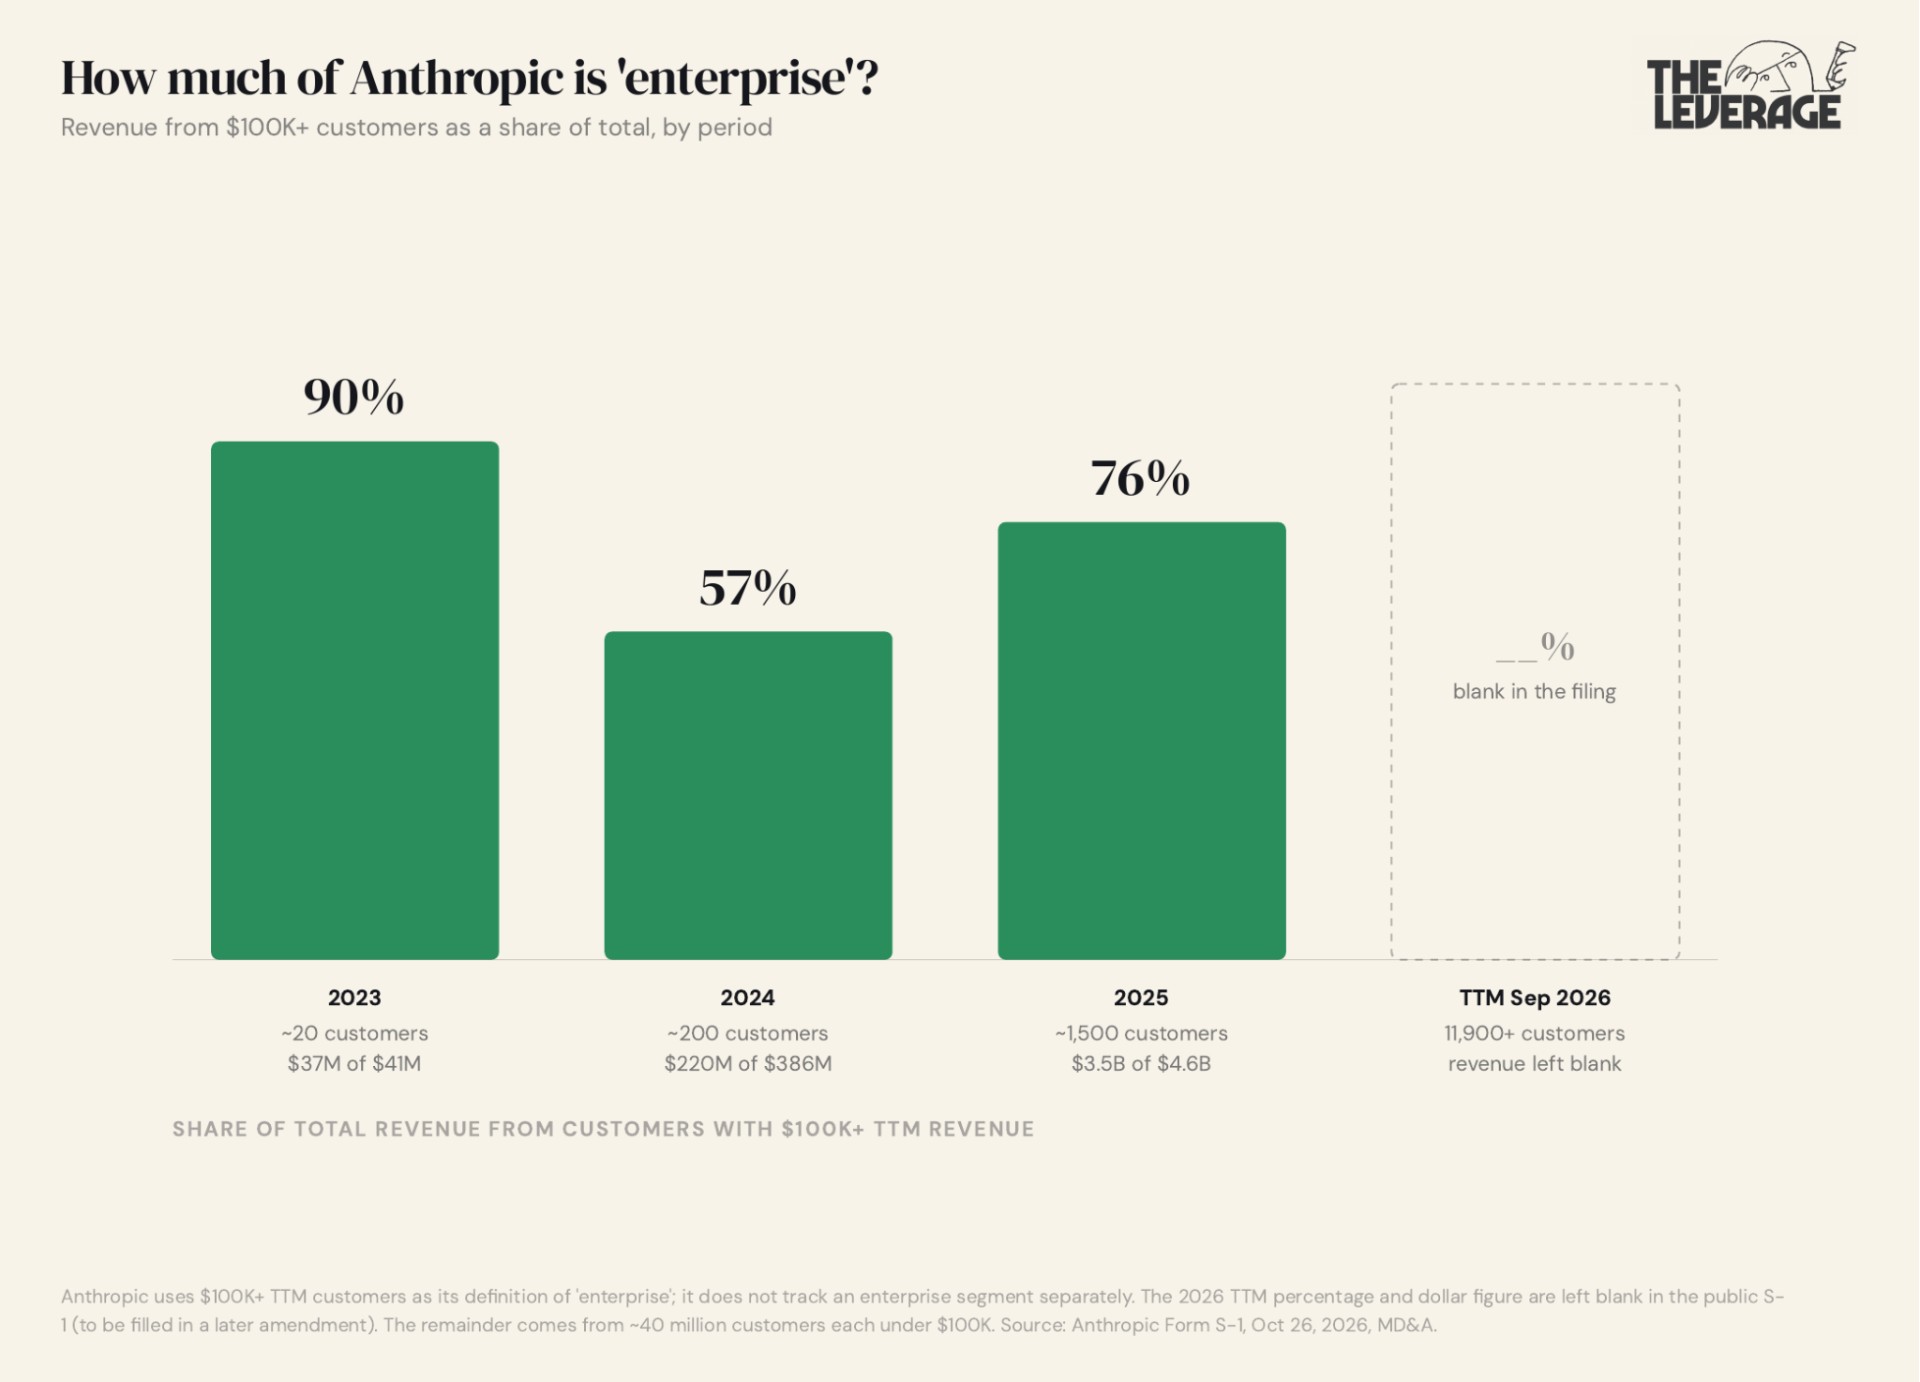
This is a usage business sold to a few thousand companies, not a software company sold to 40 million users. The S-1 defines an enterprise customer as anyone paying $100,000 a year. By that definition, 76 percent of 2025 revenue came from about 1,500 organizations, and the other 24 percent came from roughly 40 million customers combined. The ratio has held between 57 percent and 90 percent every year since launch. Think of the consumer product more as a funnel and brand.
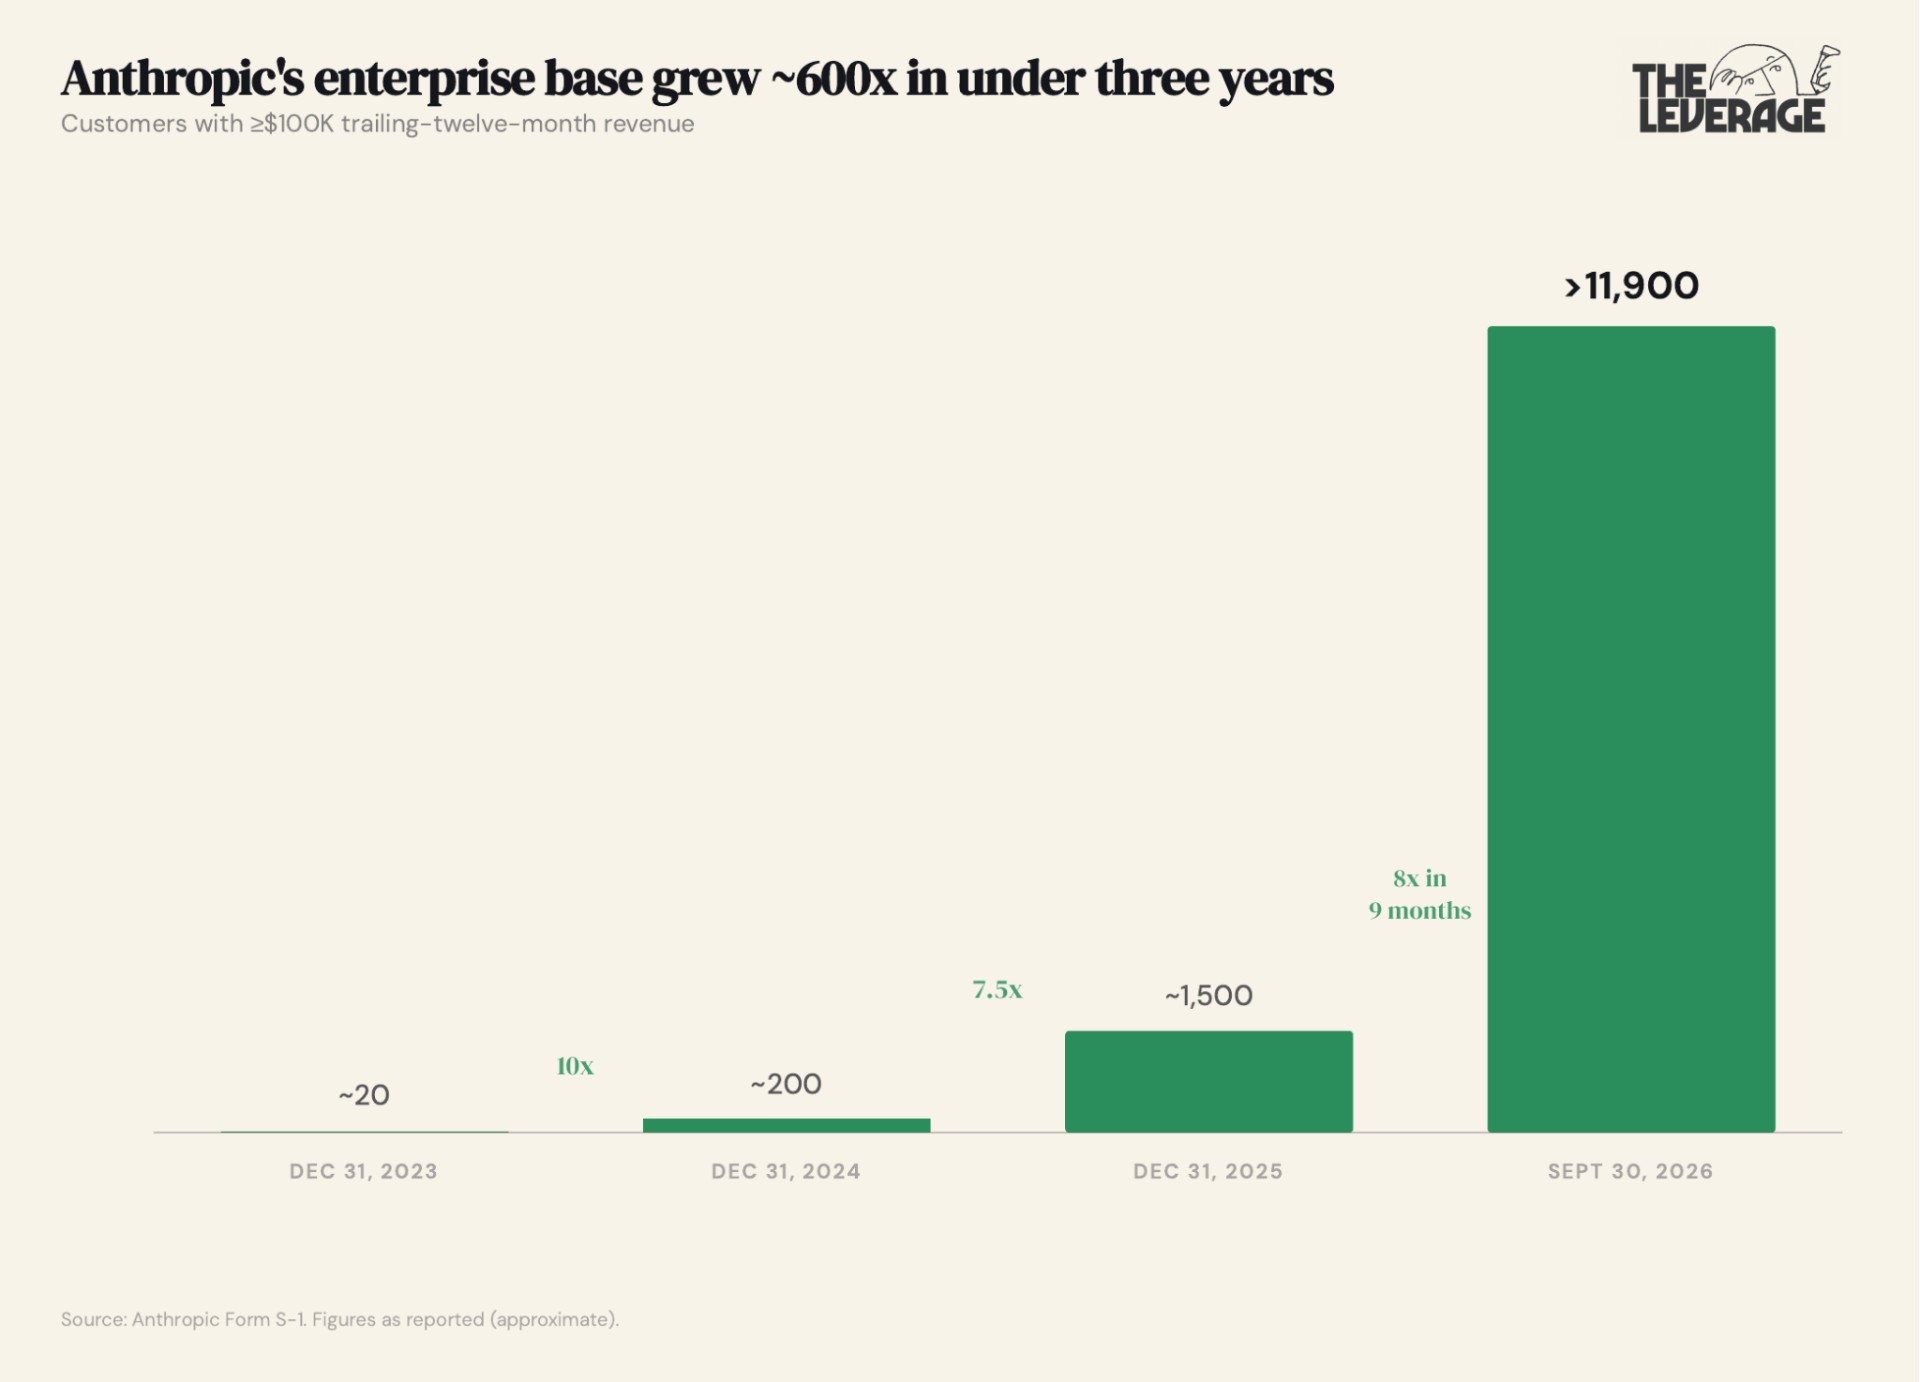
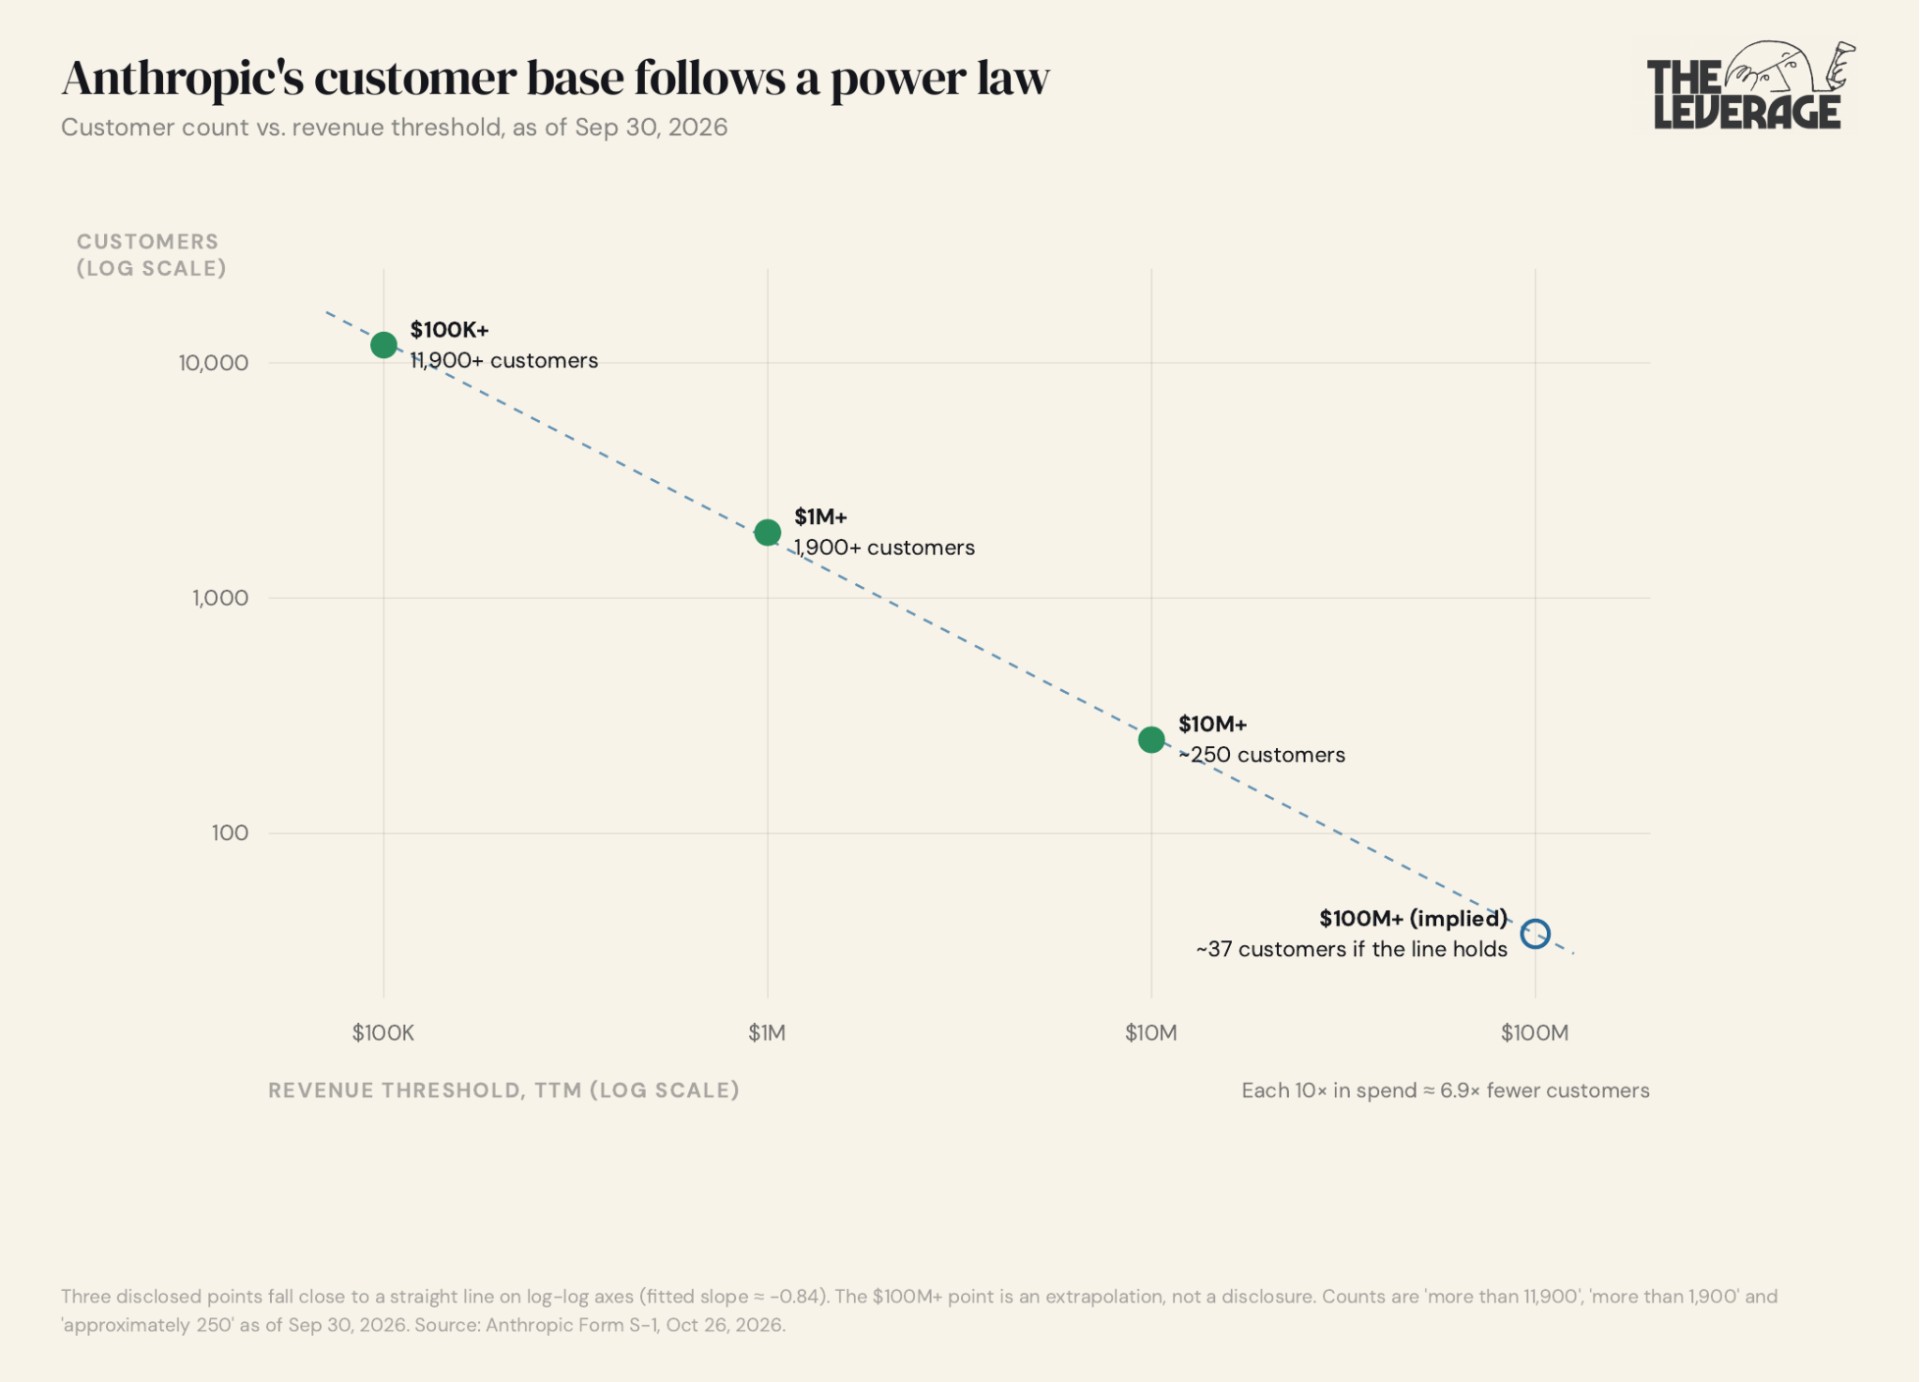
The real customer count is closer to 250 than 11,900. The 11,900 figure is the one the company leads with, and it grew eightfold in nine months, which is a legitimately absurd number.
But the tiers are a power law. Each 10x step in annual spend cuts the customer count by about sevenfold, and the line extends cleanly to an implied 30 to 40 customers above $100 million a year. If you count every one of the 11,900 accounts at the bottom of its tier, the arithmetic floor is $5.15 billion. When you underwrite this company, you are underwriting roughly 250 relationships and the rate at which the next 1,650 climb into that group.
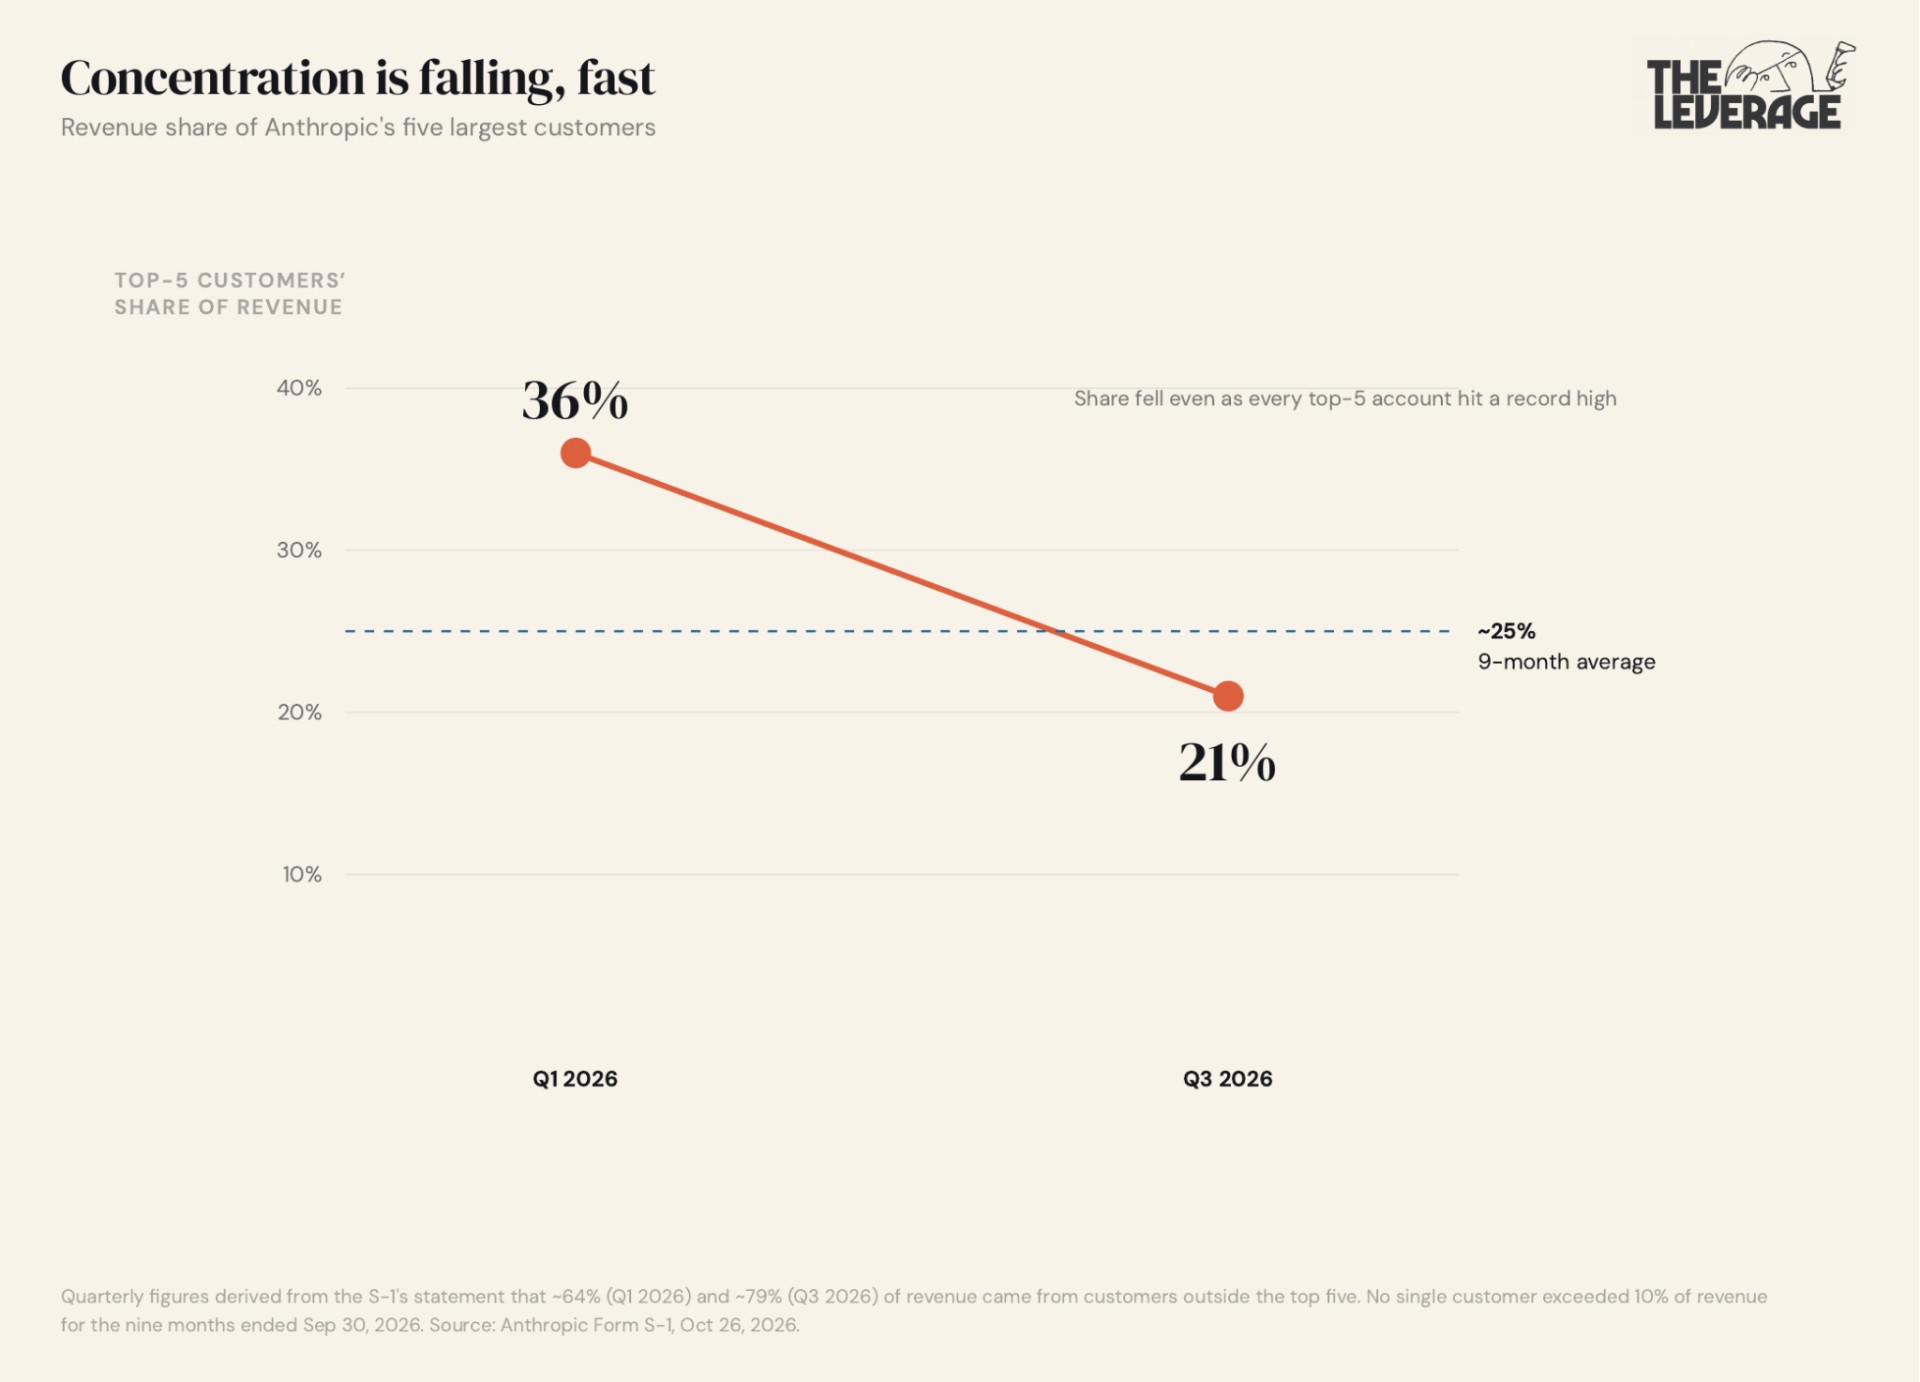
Despite that, the concentration risk is not the one in the risk factors. No single customer accounted for more than 10 percent of total revenue for the nine months prior to the filing. The top five were about 25 percent of revenue over the period, falling from 36 percent in Q1 to 21 percent in Q3 while each of the five set a record. That trend is the single best number for the bull case in the filing.
The problem is who the whales are. The reporting consensus is Cursor and GitHub Copilot, which the footnotes support in outline: Customers A and B were 12 percent each in 2025, and Customer C swung from 43 percent of revenue in 2023 to less than 10 percent to 11 percent in the first half of 2026. If that identification is right, the largest customers are coding products that sit between Anthropic and the end user, which have every incentive to route tokens to whichever model is cheapest this quarter, and whose owners (SpaceX and Microsoft, respectively) run their own model programs. The upside case is the mirror image. More than half the Fortune 500 pays Anthropic at least $100,000, and the filing says those companies spend less than 0.1 percent of their total expenses with it on average. The top 10 Fortune 500 accounts spend less than 1 percent. If the average Fortune 500 customer moved to where the top 10 already are, revenue from that cohort alone would grow eightfold. The bet at $2 trillion is that the power law keeps its shape while the whole curve shifts right.
What is gross margin anyhoo?
Surface-level analysts will likely laud Anthropic’s reported 85 percent gross margin. This would make the company a SaaS stock. However, while the company is using the SEC-accepted definition, this gross margin definition isn’t spiritually accurate.
Cost of revenue, as reported, is the compute attributed to customer-serving workloads. But Anthropic says, in its own IPO document, that it runs compute as one fungible pool. The model a customer is buying today was trained with research compute six months ago, and all the billions spent training it will be obsolete six months from now. So to properly understand this company, I think you need to treat frontier training as the cost of producing the thing being sold. If you do that by including total compute and infrastructure spend, then the cost of goods sold is $8.9 billion and gross margin is 45 percent. On that number, Anthropic is more akin to a hardware business (which is not to its benefit).
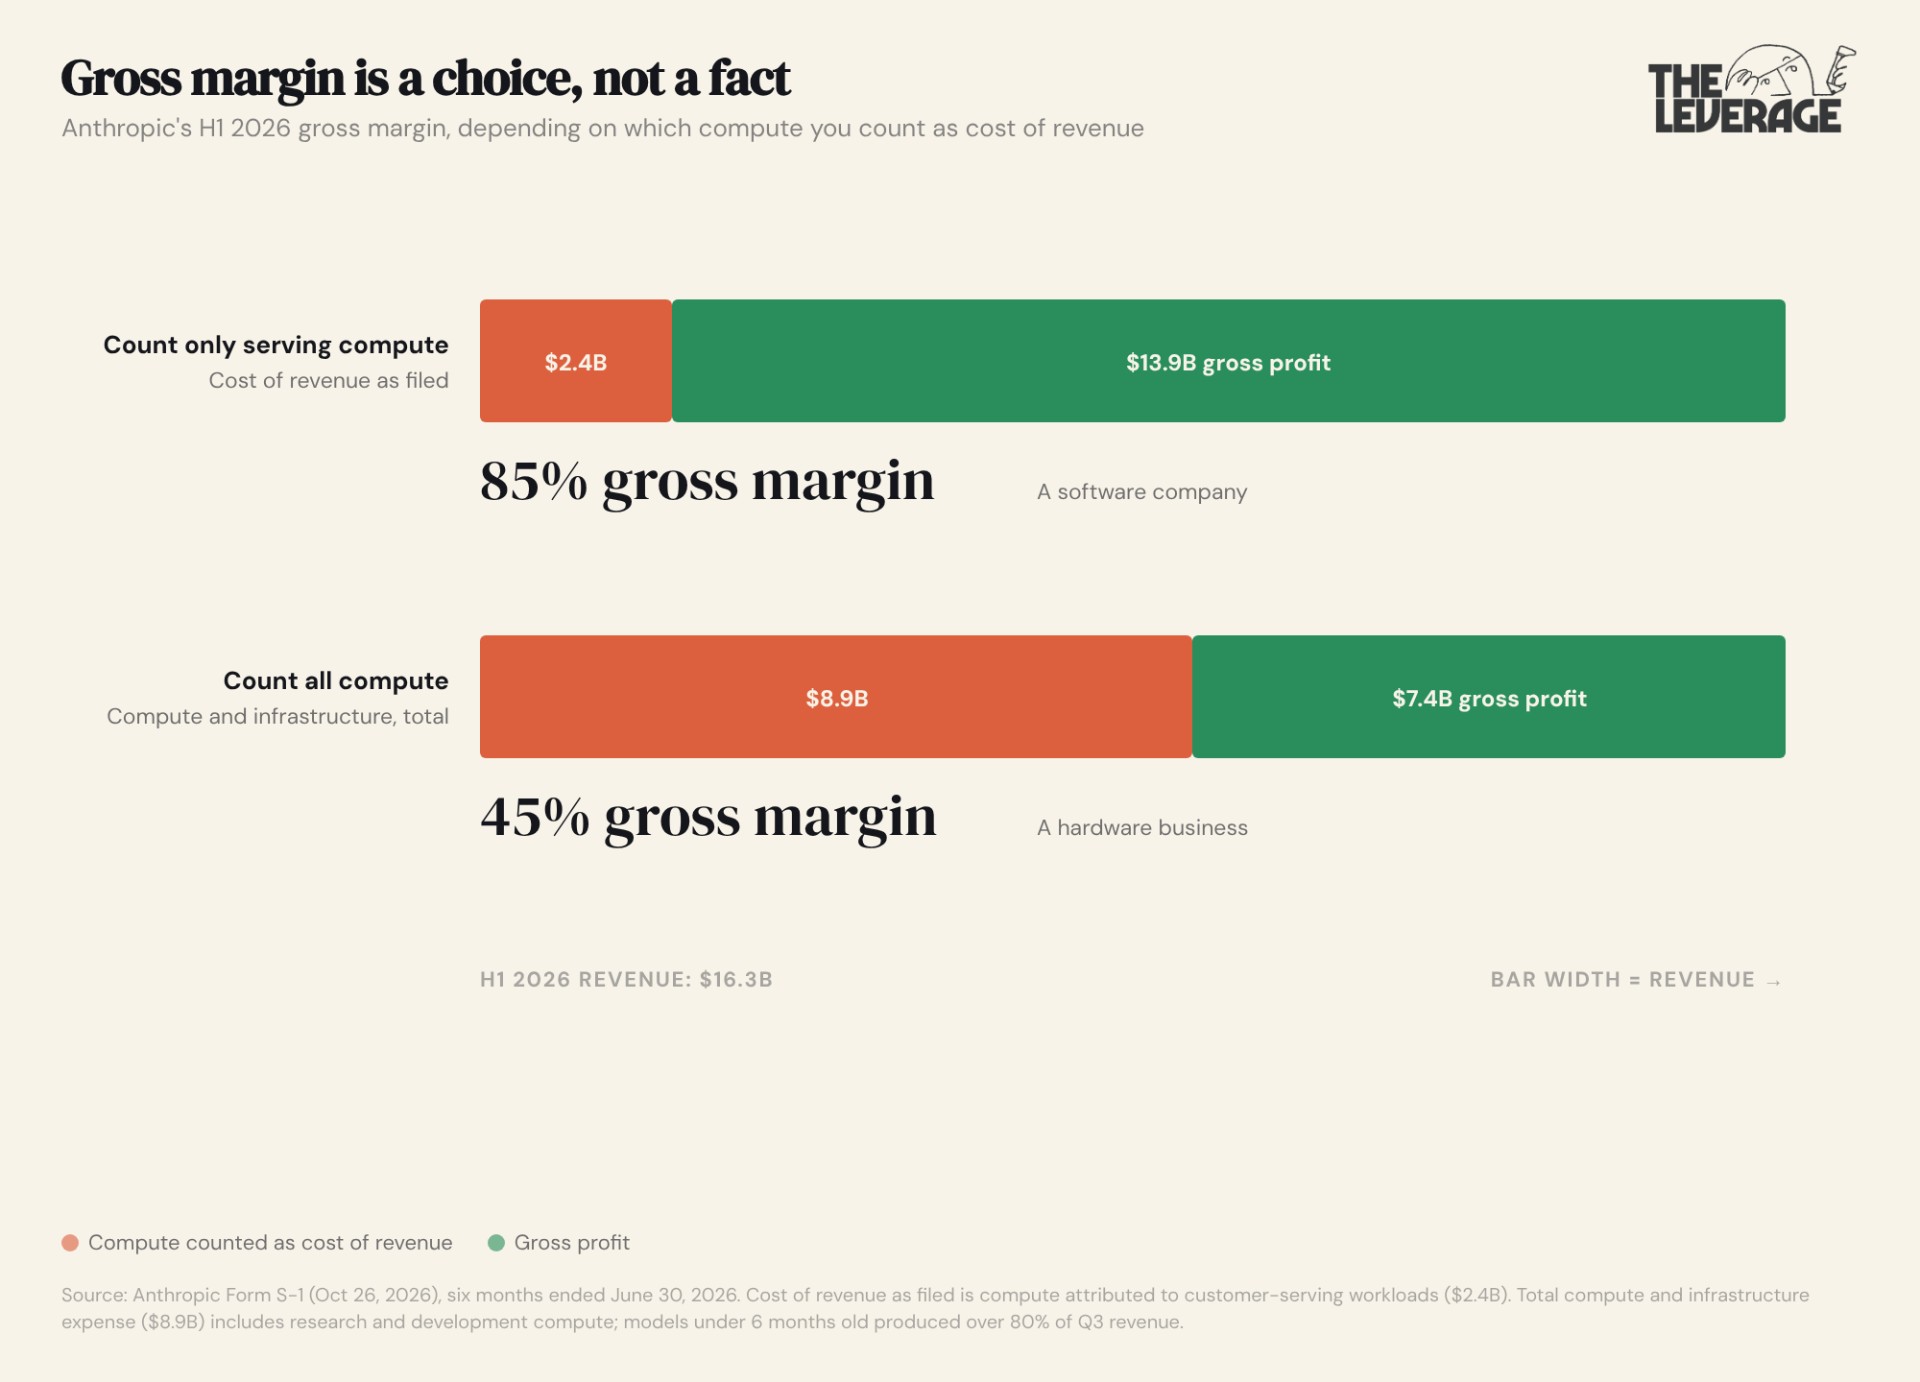
Anthropic enjoys software gross margins when serving customers while suffering hardware gross margins when it does the research necessary to stay relevant. And as we’ve already established, the second cost never goes away. The closest comparison is the Netflix content-amortization debate from 2015 to 2019, when the argument was whether original programming should be expensed or capitalized over five years. Here the content expires in six months. Unfortunately, we don’t get much more detail on the future cost of training models—most likely because Anthropic doesn’t know what it’ll be well enough to publicly commit to something. But in my conversations with researchers, most of them expect the cost increase to be logarithmic.
While we’re on the income statement, a brief note on the fact you will see in every headline. Anthropic lost “$80.7 billion” in the first half of 2026. This is a nonsense number that isn’t worth worrying about. The actual operating loss was $693 million. The loss was driven by $72.4 billion of mark-to-market losses on Amazon’s convertible notes. The notes convert at the IPO, so the loss vanishes from the P&L the quarter after listing. (This is a rare case where an $80 billion loss could easily be interpreted as a buy signal.)
The compute spend is absurd
Current compute expense is about $22 billion a year, Q2 annualized. The contracts take that to roughly $120 billion a year next year and about $155 billion by 2028, most of it non-cancelable. Revenue, meanwhile, is consumption-priced and cancelable at will, and the five largest customers are mostly not on long-term contracts. Long-term debt being married to short-term revenue makes my stomach queasy.
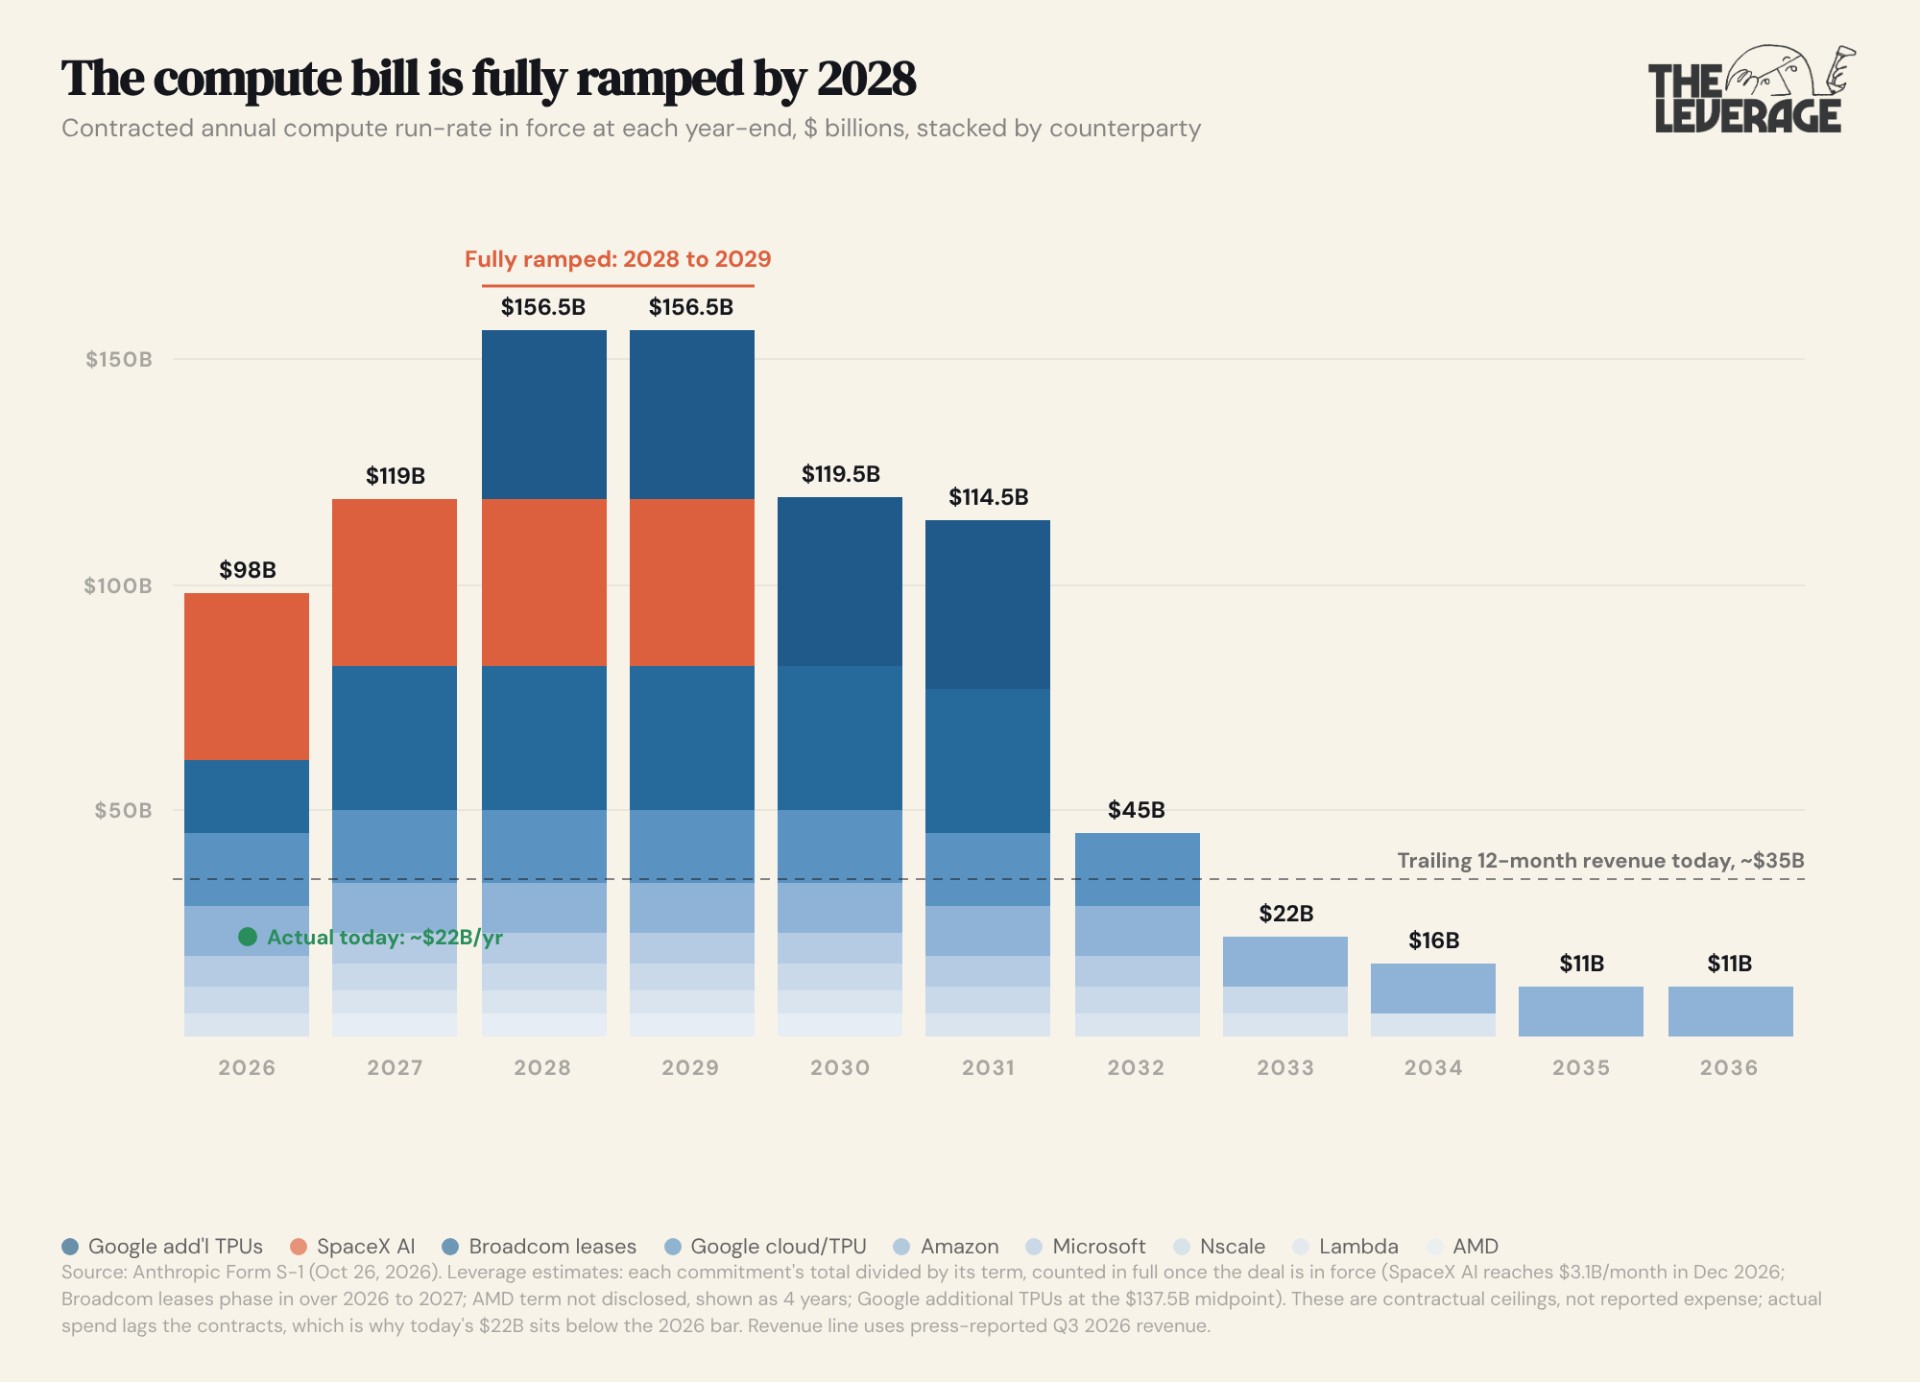
The S-1 spends a lot of time arguing that this spend isn’t a good bet. Anthropic has structured the financing program such that it separates data-center commitments (which have long lead times and bear a small share of cost) from accelerator commitments (short lead times, most of the cost), so the biggest checks get written closer to when demand is visible. To back up this plan, it dropped another shocking statistic, namely that this year, revenue grew 1,368 percent against 300 percent growth in compute. Additionally, demand has exceeded supply in every single period since Claude launched, so the risk the company has actually lived through is under-commitment, not over-commitment.
All of these points are true, yet still, it all depends on the next model being as good as the last one and Anthropic having the vertically integrated app necessary to capture that value.
Despite the big upcoming spending, the business has been remarkably efficient. The revenue per employee is $6.6 million on a trailing basis, up from $1.4 million a year earlier. Google is at $2.2 million. SpaceX, with xAI inside it, is at $1.4 million.
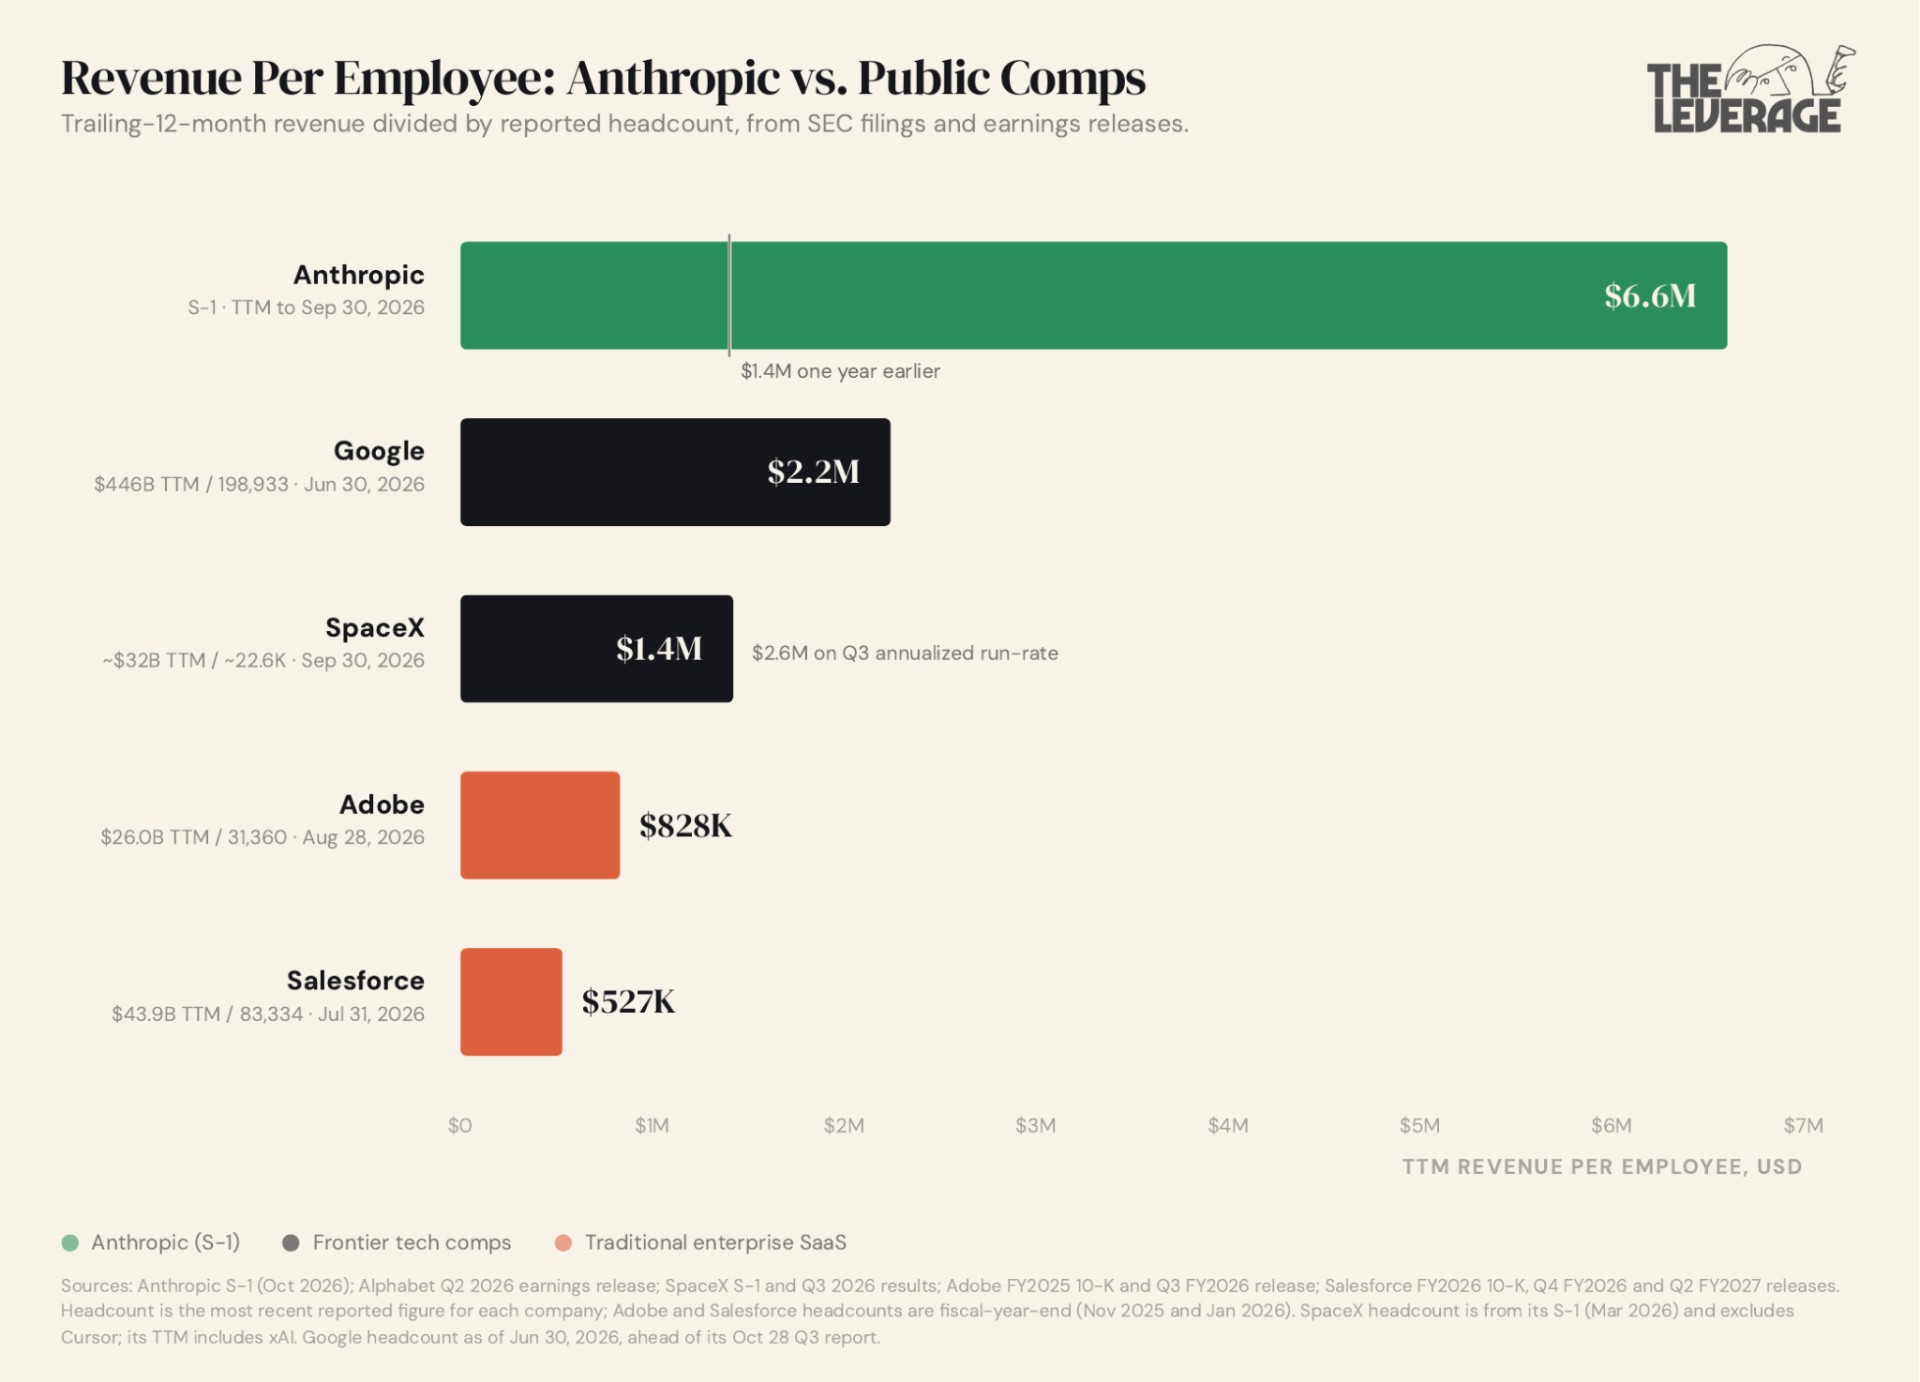
So here is where we are. The most efficient scaling in the history of the industry, 900 percent net retention, 85 percent serving margins, $131 billion in the bank, and $800 billion of fixed obligations that the company can only meet if the next six models are as good as the last six. At $2 trillion, is that a buy? It depends, again, on whether you would trust Claude to cure cancer.
The case for $2 trillion
Every business is a buy at the correct price, so we need to establish what the right price is for America’s favorite way to be lazy at work.
Q3 revenue was about $17 billion, which puts calendar 2026 around $53 billion. Here are three paths for 2027, expressed as quarterly growth that fades through the year, with compute ramping from today’s $22 billion toward the contracted $120 billion.
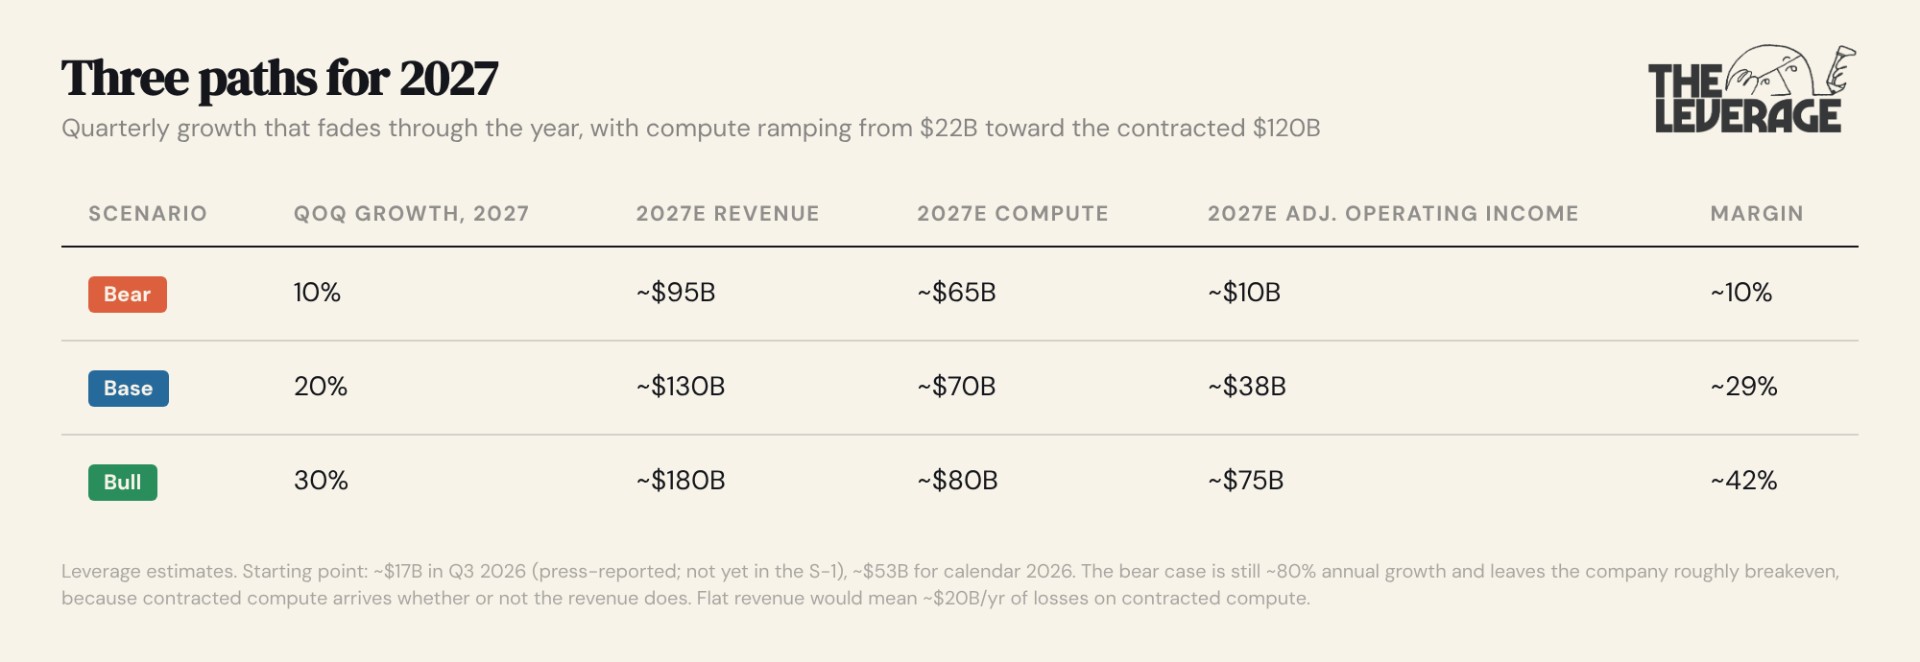
Notice the bear case is still 80 percent annual growth, and even that leaves the company roughly breakeven, because daddy AWS is going to get paid even if the revenue stops growing. If OpenAI comes back with a better model and revenue flattens, that means tens of billions in losses.
The multiples are tough to imagine, too.
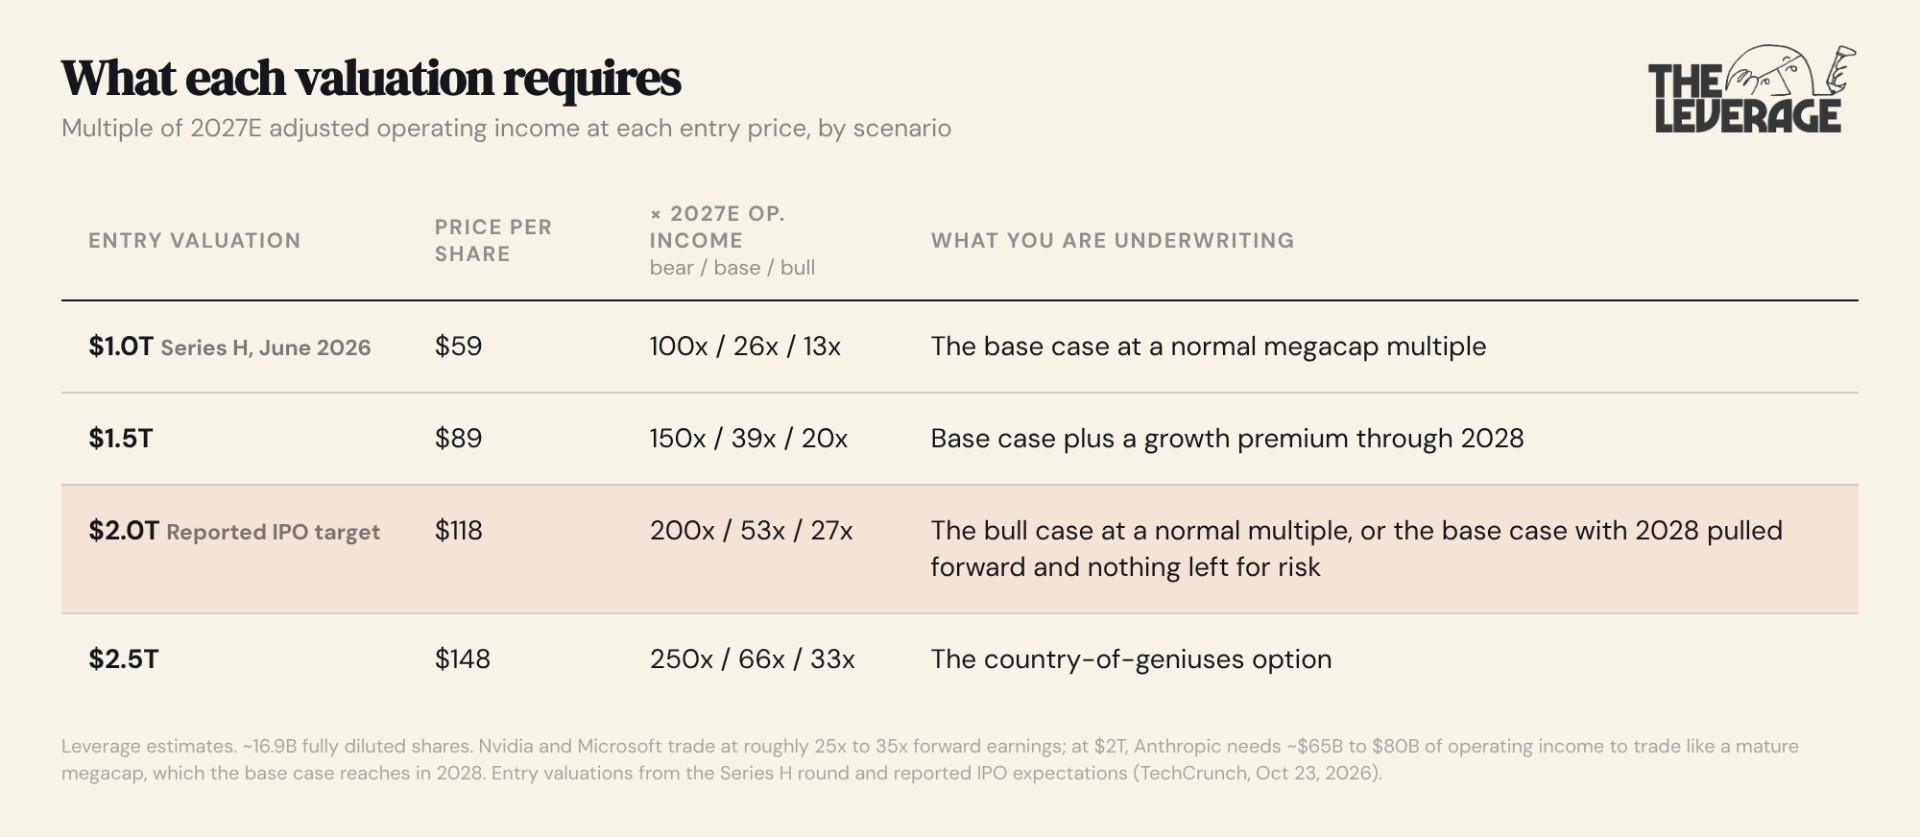
Nvidia and Microsoft trade at roughly 25 to 35 times forward earnings. To trade like a mature megacap at $2 trillion, Anthropic needs $65 to $80 billion of operating income. The base case gets there in 2028, at about $215 billion of revenue and a 30 percent margin.
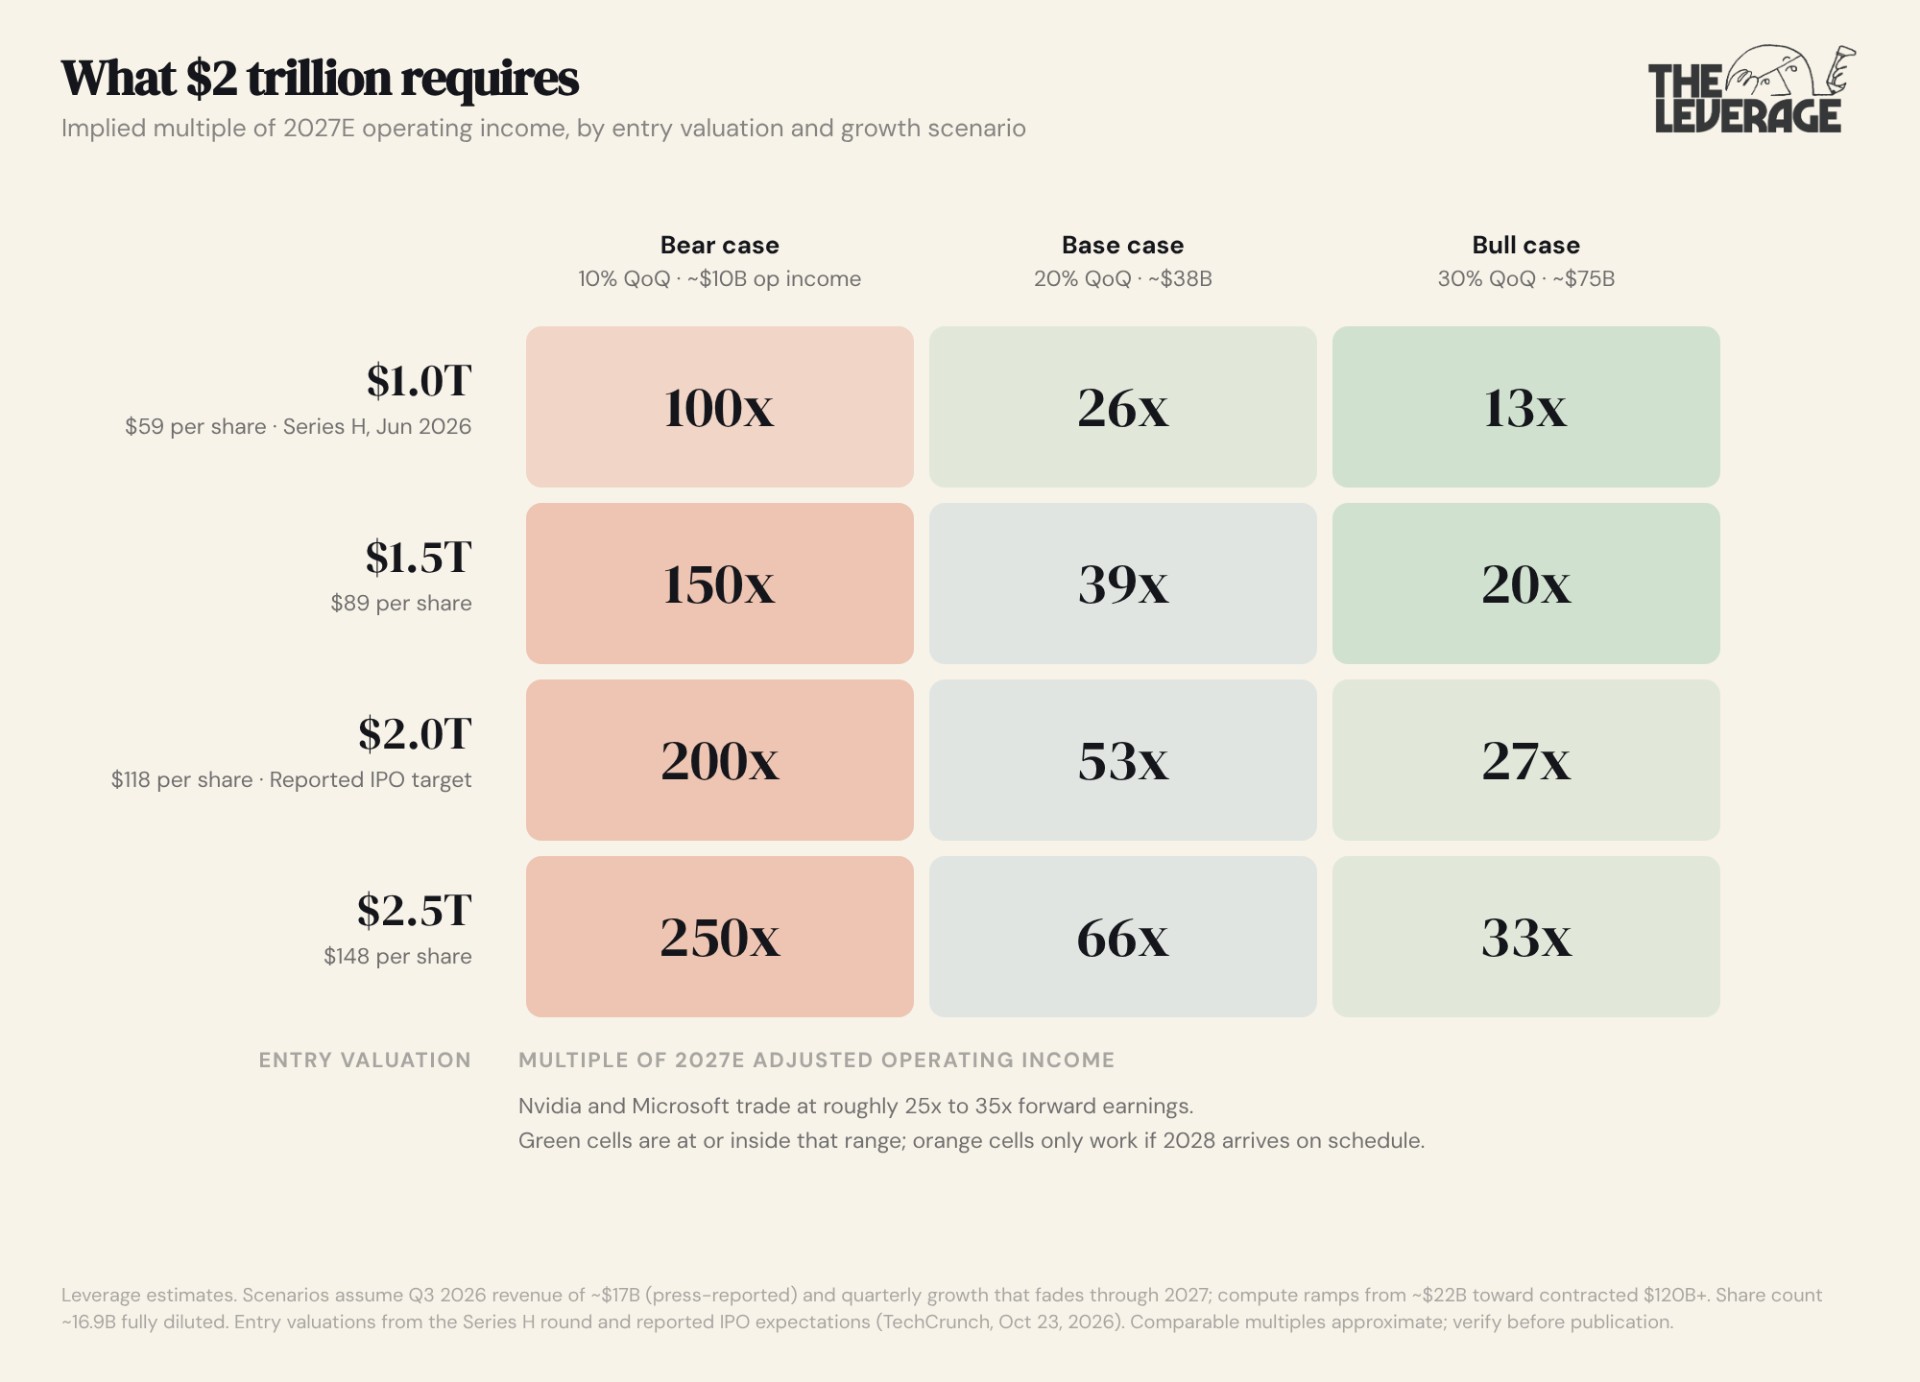
So if you buy Anthropic on IPO day at $2 trillion, you’re buying into the belief that the 2028 revenue arrives on schedule.
Anthropic is pursuing two goals at once:
1) Better coding models that grow Claude Code and that Anthropic uses to improve the models
2) Better agents that can be steered with code to do everything else
So far, the company has clearly won in the first category, but somewhat surprisingly, it’s not such a clear-cut winner in the second. Cowork, the product that is supposed to bring its AI into everyday use, is in my judgment well behind what Codex can do. Town, Grokbot, Dot, and Muse are much better personal agent products. Personal agents are a paradigm shift in how people use these models, and Anthropic does not have the same lead there that it has with the terminal.
Much of the investing decision you need to make comes down to if you believe that Claude Code gets you to $2 trillion. Producing good software is not even close to a solved problem, but much of what a junior engineer did two years ago is. When you add in that OpenAI and open-weight models are nipping at Anthropic’s heels on every software engineering benchmark that matters, I have serious reservations about Anthropic being able to keep its privileged market position into 2028. Therefore, to keep the growth curve, Anthropic has to keep launching into design, finance, and agents (which it just did with Duet), and it has to win each of those markets against competitors that are cheaper and, in some cases, better.
So is it a buy?
Either compute is the new debt or compute is the new inventory. If the models keep coming, the $800 billion is inventory that turns at 85 percent margins and $2 trillion is cheap; the base case gets you a normal megacap multiple by 2028, and the bull case makes you look like a genius. If there are just a few model generations that slip in quality, the $800 billion is debt, revenue is cancelable, and this company is toast.
Evan Armstrong is the founder of The Leverage, a newsletter that examines business strategy and power in tech markets.
Related Essays
 Katie Parrott
 Every Staff
 Kieran Klaassen
A paid Every subscriber gifted you this article. Every is a bundle of writing and tools for making sense of AI, work, and what comes next.
Subscribe to the Every bundle
Comments